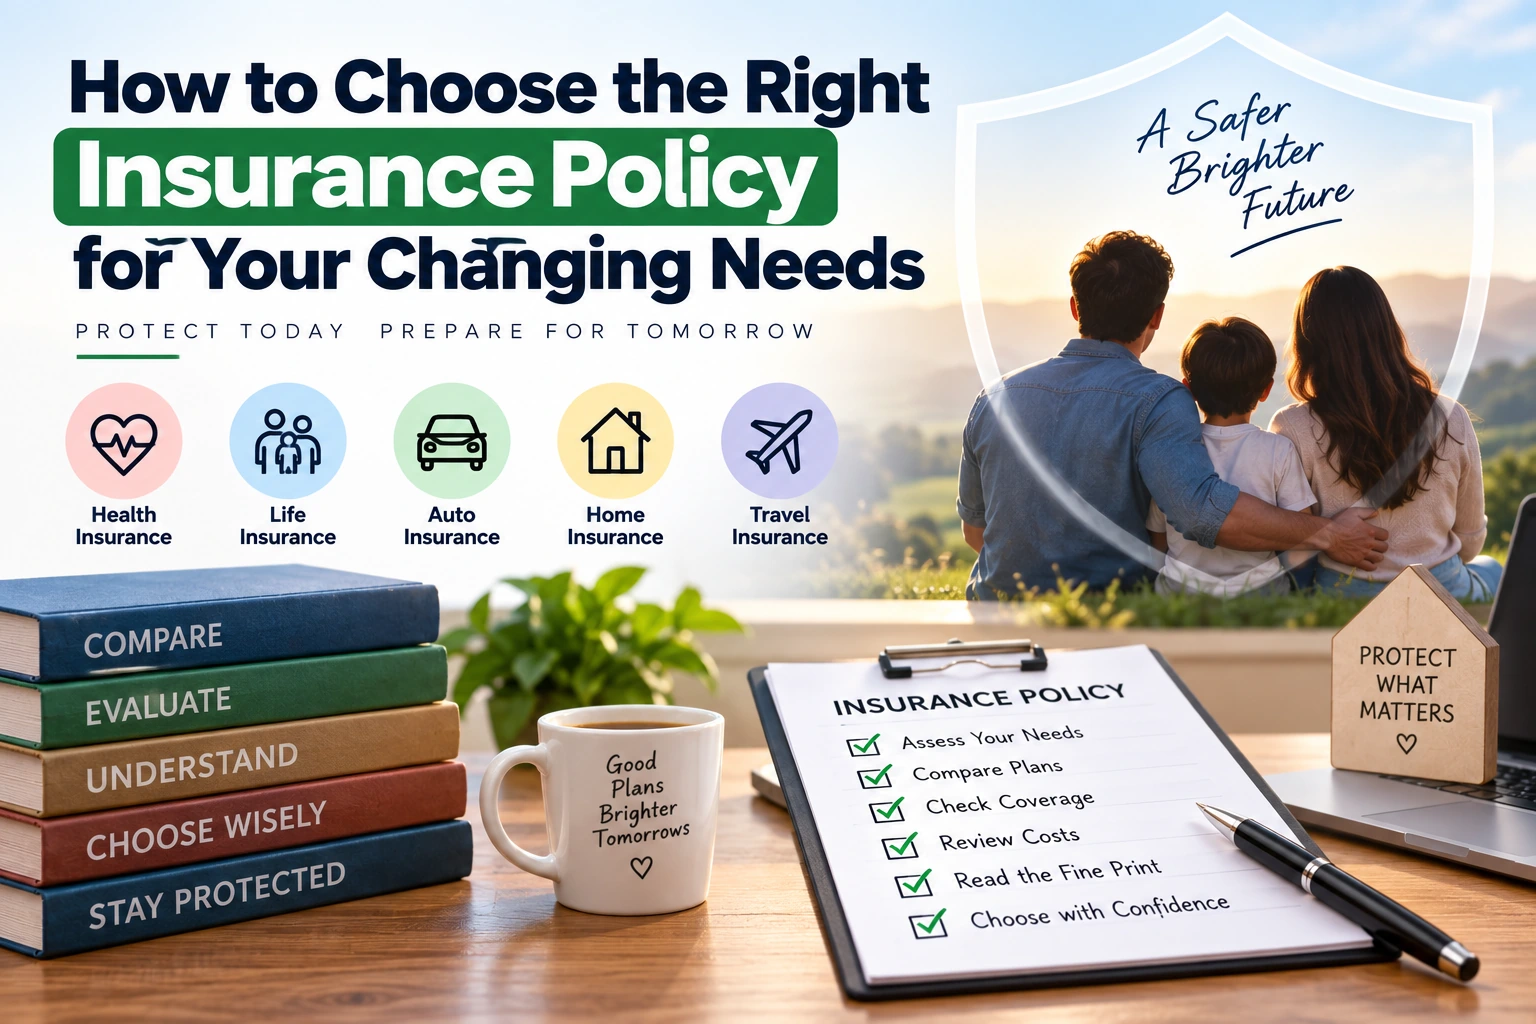
Insurance is an important part of financial planning because it can help protect individuals and families from unexpected financial burdens. However, the policy that suits someone today may not provide the right level of protection several years later. Changes in income, family responsibilities, health needs, property ownership, and long-term goals can all affect insurance requirements.
Understand What You Need to Protect
The first step is identifying the financial risks that could significantly affect you or your family. Different types of insurance address different needs.
Health insurance can help manage eligible medical expenses, while life insurance can provide financial support to dependents after the policyholder’s death. Property and vehicle insurance can help protect valuable assets against covered risks.
Understanding your priorities makes it easier to determine which policies deserve attention.
Consider Your Current Life Stage
Insurance needs often change as life circumstances change. Someone living independently may have different priorities from a person who is married, raising children, supporting parents, or approaching retirement.
For example, starting a family may increase the importance of life insurance because dependents could rely on the policyholder’s income. Purchasing a home or vehicle may introduce additional protection requirements.
Reviewing insurance after major life events can help ensure coverage remains relevant.
Evaluate Your Financial Responsibilities
Consider your current obligations when assessing coverage. These might include home loans, education expenses, household costs, business commitments, or financial support for family members.
If something unexpected happens, insurance should ideally help reduce the financial pressure created by these responsibilities. Your coverage should therefore be considered alongside your broader financial plan.
Check Coverage Amounts Carefully
Having an insurance policy does not automatically mean you have sufficient protection. The coverage amount matters.
For life insurance, consider factors such as income, outstanding debts, dependents, future expenses, and existing savings. For health insurance, examine the potential cost of medical treatment and whether the policy provides an appropriate level of protection.
Avoid selecting coverage solely because it is the cheapest option. A low premium may come with limitations that become important when you need to make a claim.
Read Policy Terms and Exclusions
Insurance policies contain conditions that determine what is and is not covered. Before purchasing, review important details such as exclusions, waiting periods, deductibles, claim procedures, coverage limits, and renewal conditions.
Do not rely only on a sales summary or advertisement. Understanding the actual policy wording can help prevent unpleasant surprises later.
If a term is unclear, ask the insurer or a qualified insurance professional to explain it before making a decision.
Compare Policies on More Than Price
Price is an important consideration, but it should not be the only factor.
When comparing policies, look at coverage, exclusions, limits, claim-related processes, flexibility, and other conditions. Two policies may have similar premiums but provide significantly different benefits.
A policy should provide meaningful protection for your specific circumstances rather than simply appearing affordable.
Review Your Health Insurance Needs
Healthcare requirements can change over time. Age, family size, medical needs, and healthcare costs may influence the amount and type of coverage that makes sense.
When reviewing a health policy, consider factors such as hospitalization coverage, applicable waiting periods, network facilities, room-related limits, exclusions, and renewal terms.
If your family has expanded, check whether existing coverage adequately accounts for additional members.
Reassess Life Insurance After Major Changes
Life insurance should be reviewed when your financial responsibilities change. Marriage, having children, purchasing a home, starting a business, receiving a major income increase, or approaching retirement can all be reasons to reassess your protection.
The objective is to make sure your policy continues to align with the financial needs of the people who depend on you.
Avoid Being Overinsured or Underinsured
Too little insurance can leave you exposed to significant financial risk. However, buying excessive coverage can also place unnecessary pressure on your budget.
A balanced approach considers your actual risks, responsibilities, income, assets, savings, and financial goals. Your coverage should be sufficient without becoming financially difficult to maintain.
Review Your Policies Regularly
Insurance should not be treated as a “set it and forget it” purchase. Review your policies periodically and whenever your circumstances change.
Check whether beneficiaries, contact details, coverage amounts, and personal information are still accurate. Also consider whether changes in income, family responsibilities, assets, or financial goals require adjustments.
Conclusion
Choosing the right insurance policy is about matching protection with your current and future needs. Instead of focusing only on premiums, consider coverage levels, exclusions, policy conditions, affordability, and your changing financial responsibilities.
Regular reviews are equally important. As your life evolves, your insurance should evolve with it. Taking time to understand your coverage and reassess it after major life events can help you maintain appropriate financial protection and greater confidence in your overall financial plan.